
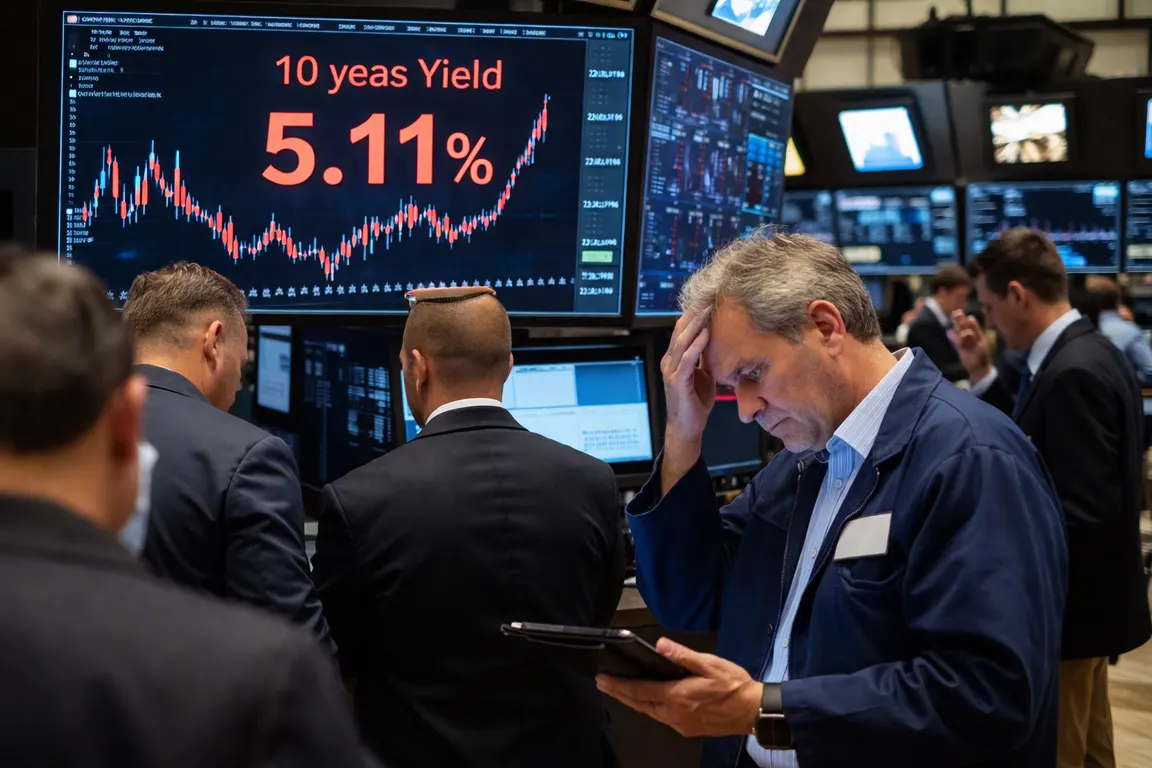
The 10‑year U.S. Treasury yield rose to 5.11% on Sept. 24, the highest level since 2007, signaling a sharp increase in borrowing costs for households, businesses and the federal government.
Higher yields raise discount rates used in equity valuations, lift mortgage and corporate loan rates and tighten margin‑debt financing at a time when U.S. debt has passed $40 trillion and geopolitical tensions are adding a risk premium to fixed‑income markets.
The move was broad‑based. The 30‑year Treasury climbed to about 5.4% and the two‑year to roughly 4.9%, pushing the entire yield curve upward. The Congressional Budget Office projects a $1.9 trillion deficit for fiscal year 2026 and a debt‑to‑GDP ratio near 101%. Retail‑investor margin debt, tracked by FINRA, jumped 37% year‑over‑year to $1.45 trillion in August, indicating that leveraged positions are expanding even as capital becomes more expensive.
Japan offers a contrast. In July its headline CPI was 1.9% year‑over‑year, with core inflation at 1.7%, well below the United States’ 3.4%/2.4% rates. Yet Japanese sovereign debt remains about 1.6 times GDP, largely held by domestic investors, and the Bank of Japan lifted its policy rate to 1.25% in mid‑September. The Japanese case shows that high debt does not automatically spark inflation, but it can lock an economy into low‑growth, low‑inflation stagnation.
Across other major economies, bond yields moved in step with U.S. rates: Canada’s 10‑year hit 3.95%, the United Kingdom’s 10‑year rose to 5.35%, Australia’s 10‑year to 5.38%, Germany’s 10‑year settled at 3.55%, France’s at 4.66% and Japan’s at 3.05%. The synchrony reflects a broader risk‑off shift driven by heightened Middle‑East oil price pressure, renewed U.S.–China AI talks and the ongoing Russia‑Ukraine conflict, all of which have added a risk premium to sovereign debt.
For investors, the immediate impact is threefold. First, higher Treasury yields increase the discount rate in equity models, compressing price‑to‑earnings multiples and making growth stocks especially vulnerable. Second, corporations face steeper borrowing costs, which could delay capital‑expenditure projects and hiring, particularly in sectors that rely on long‑dated financing. Third, the surge in margin debt means a modest equity correction could trigger forced liquidations, amplifying price declines.
Ordinary Americans are already feeling the ripple effects. Mortgage rates have climbed above 7%, and banks are tightening credit as they adjust loan pricing to the new funding environment. The $40 trillion debt pile could eventually force policymakers to consider spending cuts or tax adjustments, adding uncertainty for households and public services.
The situation remains fluid. The Federal Reserve has not signaled a change in policy, and no yield‑curve control measures have been announced. Market participants will watch upcoming Treasury auctions, the Fed’s next policy meeting and any fiscal legislation aimed at reducing the deficit. How Washington balances fiscal consolidation with the risk of choking growth will determine whether the current “perfect storm” leads to a sharp equity correction or a more gradual adjustment.