Russian diesel waiver and market reaction to French riots
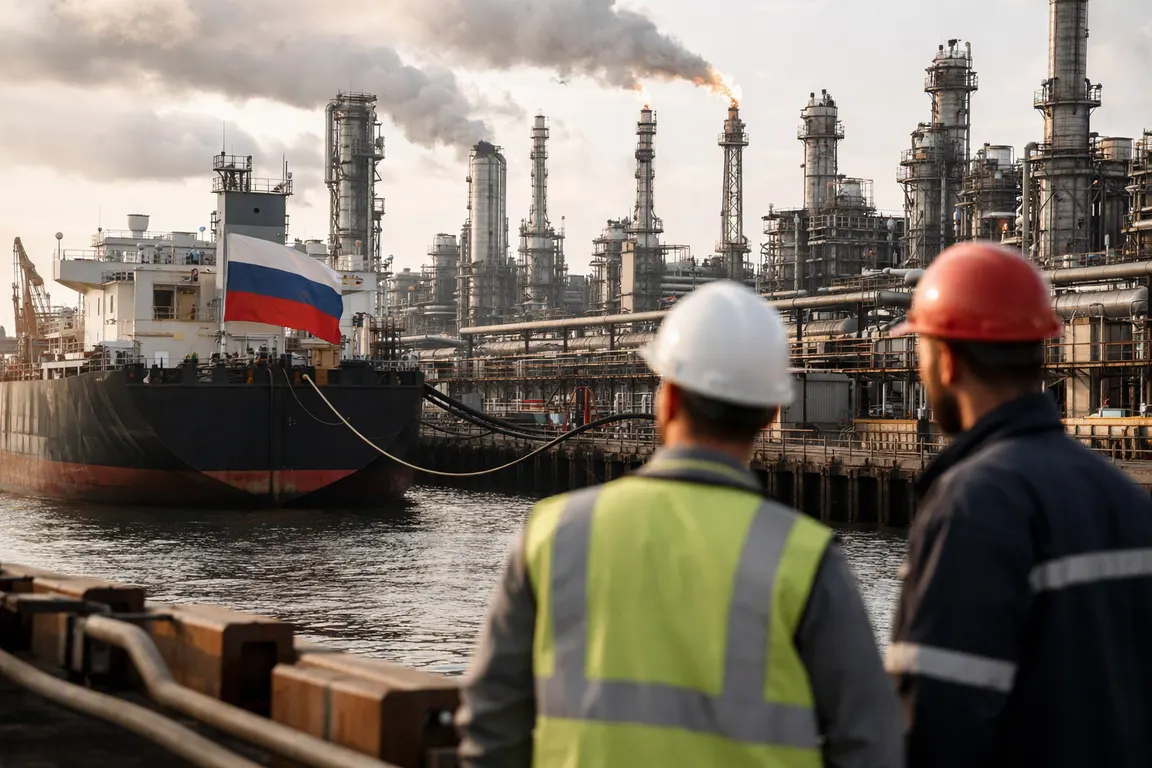
President Donald Trump signed an executive order on Oct. 18 that temporarily lifts Graham Act sanctions and tariffs on Russian diesel, allowing up to 300,000 tonnes to enter the United States for 60 days. The Russian diesel waiver was presented as a tool to keep Moscow at the bargaining table and immediately eased short‑term supply concerns for U.S. refineries.
The policy shift coincided with a 1.2% dip in Brent crude to $108.59 a barrel and a modest rise in the 10‑year Treasury yield to 5.07%, nudging equities lower and widening sovereign‑bond spreads. The Treasury curve also steepened as the 2‑year yield fell three basis points, reflecting uncertainty ahead of the mid‑term elections.
At the same time, violent protests swept France. The interior ministry reported roughly 2,400 arrests and about 1,000 police injuries after riots spread from Paris to cities such as Limoges, where the historic town hall was set ablaze. The unrest pushed the CAC 40 down 1.3% and widened the French 10‑year OAT‑Bund spread to 146 basis points, the widest in two weeks. The broader Stoxx 600 slipped 0.7% as European bond investors demanded a higher risk premium on French debt.
In the Gulf, a series of attacks on shipping in the Strait of Hormuz added another layer of risk. Twelve vessels were reported attacked between Oct. 4 and Oct. 11, and two tankers caught fire after striking mines. The Strait handles roughly a third of global petroleum shipments, and traders are now pricing a premium for Gulf‑sourced crude, a factor that could heighten price volatility if attacks continue.
The three shocks intersect with electoral calendars. The U.S. waiver expires just after the mid‑term vote, making energy‑price policy a likely issue for candidates and voters. In France, the riots arrive ahead of the 2027 presidential race, where public‑order credibility and fiscal discipline are expected to dominate campaign narratives.
Investors are watching several fronts. Consumer‑discretionary, transportation and industrial sectors could feel the impact of any swing in fuel prices once the waiver lapses. Bond fund managers are monitoring sovereign‑spread movements tied to political stability in both the United States and France. The next week of data on U.S. oil inventories, Treasury yields and French fiscal statements will shape market direction.
In the short term, market participants must gauge how quickly the temporary relief from Russian diesel will fade and whether further escalation in the Gulf or additional unrest in France will sustain pressure on equities, bonds and commodities. The convergence of policy, geopolitics and domestic unrest creates a multi‑front risk environment that will test investors’ appetite for volatility in the weeks ahead.