
Oil Price Spike Pushes Treasury Yields Near 20‑Year High
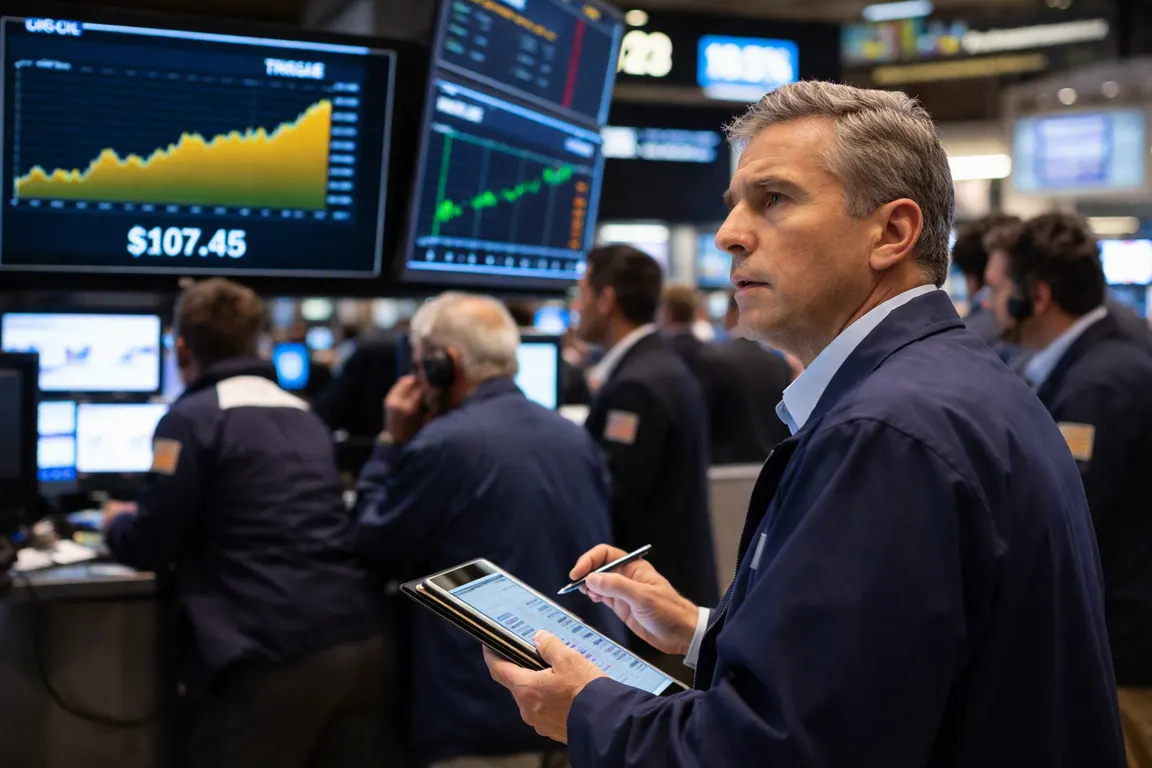
Oil prices jumped above $107 a barrel on Thursday after President Trump dismissed Iran’s latest offer to reopen the Strait of Hormuz. The move sent the 10‑year Treasury yield to a near‑two‑decade peak of 5.21‑5.23 percent and lifted the market’s estimate of a Federal Reserve rate hike in October to roughly 70 percent, up from 53 percent a week earlier.
Higher oil costs immediately affect consumers and businesses. Gasoline prices are set to rise, squeezing household budgets, while logistics firms face higher operating expenses. At the same time, soaring Treasury yields increase borrowing costs for mortgages, corporate debt and municipal financing. A bond sell‑off has already prompted asset managers to shift $25‑30 billion from equities into higher‑yielding Treasuries, tightening liquidity in equity markets just as the Fed’s policy path remains uncertain.
The Fed now faces three overlapping pressures. First, the oil shock could lift headline inflation even as core price pressures stay modest. Core PCE for August is projected to rise 0.27 percent month‑on‑month, with year‑over‑year core inflation near 3.2 percent—still above the Fed’s 2 percent target but not dramatically so. Second, the labor market is poised to release September non‑farm payrolls, with forecasts ranging from 45,000 to 80,000 jobs and unemployment expected to hold at 4.1 percent. A strong jobs report would suggest the economy can absorb tighter policy; a weaker one could prompt caution. Third, market expectations for an October rate hike have jumped to 70 percent, reflecting investor anxiety that the Fed may need to act decisively.
Former Fed official Scott Bessent, speaking on Fox News, urged the central bank to stay “open‑minded,” noting that AI‑driven productivity gains could help offset oil‑driven price pressures. While the quote appears in several outlets, it has not been independently verified. Several Fed officials slated to speak this week—including Thomas Barkin, Michelle Bowman, Philip Jefferson and Christopher Waller—have warned that supply‑side shocks could outweigh any productivity offset, underscoring the uncertainty surrounding the policy outlook.
Investors are already feeling the pressure. The rapid bond market sell‑off has forced fund managers to move cash from equities into Treasury securities, a shift that could dampen equity valuations at a time when corporate earnings are contending with higher input costs. For consumers, the combination of higher gasoline prices and rising mortgage rates threatens to squeeze disposable income, potentially slowing the housing market and curbing spending on durable goods.
The coming week will test the Fed’s resolve. Speeches from Barkin, Bowman, Jefferson and Waller begin on Sept. 28, followed by consumer confidence and JOLTS data on Sept. 29, and core PCE, personal income and spending figures on Sept. 30. The ISM manufacturing index arrives on Oct. 1, and the crucial non‑farm payrolls report lands on Oct. 2. Each data point will either reinforce the case for a rate hike or provide a rationale for a more measured approach.
As policymakers weigh the oil‑driven inflation spike against still‑moderate core price trends and a labor market that may be softening, the Fed’s next move will shape borrowing costs for households and businesses alike. Whether productivity gains can truly offset the energy shock remains an open question, but market expectations suggest the Fed’s policy lever is already walking a tightrope.