
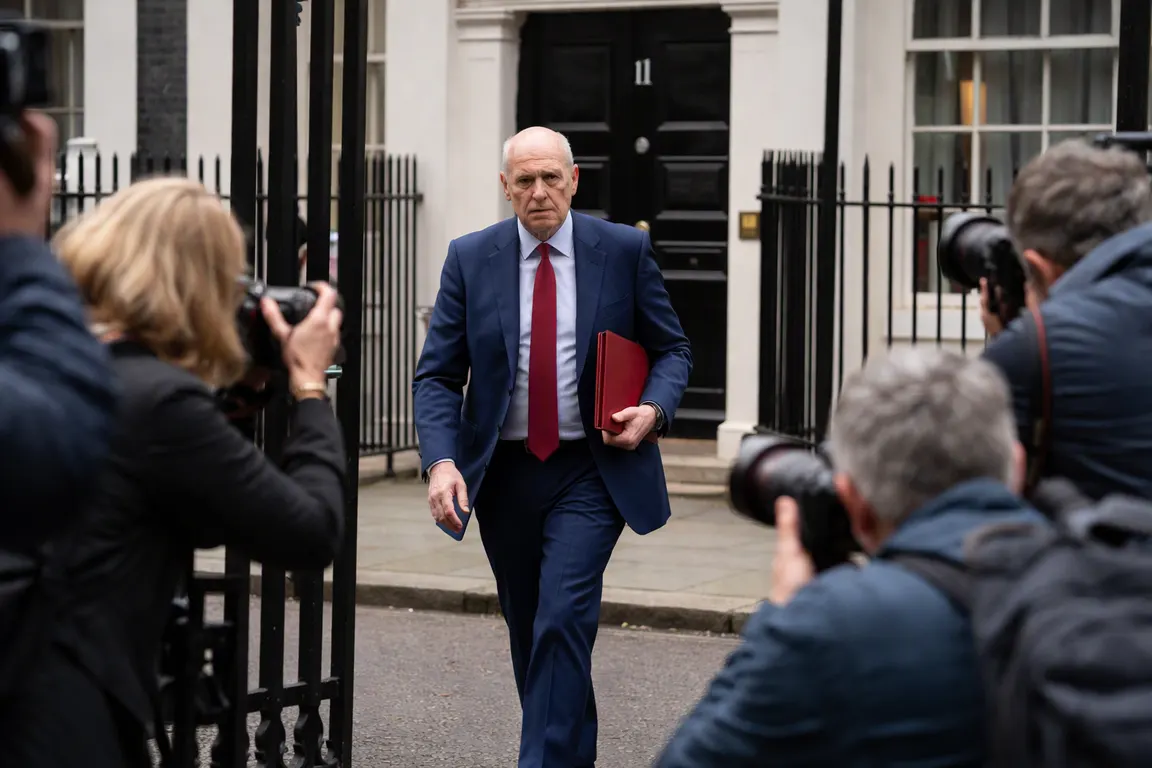
Public‑sector net borrowing jumped to £18.3 billion in August, £2.9 billion more than a year earlier and above market forecasts, the Office for National Statistics said on Tuesday. The surprise comes weeks before Chancellor John Healey delivers the October 2024 budget, reviving scrutiny of the government's deficit‑reduction narrative.
The higher‑than‑expected borrowing could push gilt yields up, increasing borrowing costs for the state and households. With the budget looming, the Treasury will need to explain a fiscal picture that is less tidy than the one it has been presenting in recent months.
BBC News, The Guardian and the Wall Street Journal all reported the ONS figure and noted that it missed analysts' expectations. The Guardian warned of potential strain on bond‑market stability, the Wall Street Journal called the year‑on‑year rise a setback to the deficit‑reduction plan, and the BBC linked the increase to inflation‑driven pressures on public spending. None of the outlets disclosed the precise baseline forecast, leaving the size of the miss open to interpretation.
The £18.3 billion tally pushes the cumulative deficit for the current fiscal year above the £100 billion threshold that officials have cited as a marker of fiscal prudence. If gilt yields respond to the surprise by edging higher, the government could face a larger interest bill, further tightening the deficit trajectory.
Analysts say the rise may reflect a mix of higher inflation‑linked outlays and slower tax receipts, though the ONS has not broken down the drivers. The data arrived after the Treasury’s mid‑year review, which had signalled a modest improvement in the deficit outlook, intensifying scrutiny of the upcoming budget.
Bond market participants have already priced the surprise into gilt yields, which rose modestly in the days following the release. A sustained upward trend could translate into higher mortgage rates and costlier corporate financing, feeding through to consumer spending and business investment. For taxpayers, the indirect effect could be a slower recovery in disposable income if the Treasury opts for tighter fiscal measures later in the year.
No new spending cuts or tax changes have been announced since the August data emerged, and officials have stressed that the figure reflects temporary pressures rather than a shift in policy direction. Nonetheless, the chancellor will be expected to explain the deviation from forecasts, outline steps to contain future borrowing and reassure markets that the deficit path remains on track.
As the October budget approaches, the key question is whether the Treasury can restore confidence without imposing measures that further burden households. The answer will shape not only short‑term gilt yields but also the broader narrative of fiscal responsibility the government has been promoting throughout the year.